
The Hidden Cost of Reactive Decision-Making
Most investors do not lose money because they chose the wrong assets. They lose money because they make the right decision at the wrong time — buying after prices have already risen, selling after they have already fallen, or abandoning a strategy during the exact period when patience would have paid off. Reactive decision-making is the single most expensive cognitive habit an investor can develop.
Research by DALBAR consistently shows that the average equity investor underperforms the market index by 3–4% annually over 20-year periods — not because they selected poor funds, but because of poor timing driven by emotional reactions. The difference between what the market returns and what the average investor actually earns is called the “behavior gap,” a term popularised by financial planner Carl Richards. That gap is not a market problem. It is a psychology problem.
Mastering investment decisions means closing this behavior gap. It means building enough process between stimulus and response that emotion becomes an input to consider rather than a trigger to obey. Every structured technique — checklists, pre-commitment, the 3A framework — exists to create that gap and fill it with deliberate thinking.
Decision Quality vs. Decision Outcomes
One of the most important distinctions in investment psychology is the difference between decision quality and decision outcome. A good decision can produce a bad outcome; a bad decision can produce a good outcome. The market is noisy enough in the short term that luck and skill are nearly indistinguishable over periods of less than five years. This creates a dangerous feedback loop: investors who made poor decisions that happened to work out feel validated, reinforcing the same poor process. Investors who made sound decisions that temporarily underperformed may abandon a working strategy.
Evaluating your investment process by its outcomes alone is like evaluating a chef by whether the diner enjoyed their meal — there are too many uncontrollable variables. The right question after every investment decision is not “did it work?” but “was the reasoning sound given what I knew at the time?” A disciplined investor who loses 8% in a market downturn while following their strategy made a better decision than an undisciplined investor who made 15% by guessing correctly on a speculative trade.
Building this distinction into your thinking is one of the most psychologically challenging aspects of long-term investing. It requires that you trust process over results — especially when short-term results are poor — and evaluate your decisions on the quality of the reasoning, not the pleasure or pain of the outcome.
When to Override Your System — and When Not To
A well-designed decision framework raises an uncomfortable question: when, if ever, should you deviate from it? There is a version of disciplined investing that becomes rigid and fails to adapt to genuinely new information. There is another version where every deviation is rationalized as “new information” when it is actually just emotion in disguise.
The practical answer is to distinguish between pre-specified conditions and in-the-moment reactions. A robust investment process should include explicit criteria for when the strategy may legitimately change — new research, a fundamental change in a company’s business model, a change in your own financial situation. These are planned decision points, reviewed calmly and without market pressure.
What should not override your system is price movement alone. Stocks falling 20% is not new information — it is expected volatility that your strategy should already account for. Stocks rising sharply is not a reason to increase risk exposure beyond your planned allocation. The moment you find yourself updating your strategy in response to recent price action, you are likely being driven by emotion rather than analysis.
The discipline to distinguish between these two types of updates — legitimate strategic revision versus emotional rationalization — is what separates investors who improve over time from those who repeat the same mistakes in new market cycles.


Introduction
Making the perfect decision when starting an investment or opening a trade is one of the biggest psychological challenges for both beginners and experienced traders. The fear of losing money, the pressure of timing the market, and the noise of contradictory information can paralyze even the most disciplined investors.
In this guide, you’ll learn a step-by-step, psychology-driven framework to evaluate opportunities with clarity, confidence, and precision. We’ll explore how emotions shape your decision-making, how to build a repeatable process, and how to reduce hesitation — so every trade or investment becomes intentional rather than impulsive.
Why Most Investors Struggle to Make Good Decisions
1. Emotional Biases That Distort Investment Choices


Even skilled traders fall into emotional traps. Some of the most common include:
- Fear of Missing Out (FOMO) leads to rushed entries.
- Loss aversion makes you avoid great opportunities because of past losses.
- Overconfidence pushes you into oversized positions.
- Confirmation bias makes you seek information that supports your preferred direction.
These biases don’t mean you’re inexperienced — they mean you’re human. The goal isn’t to eliminate emotions, but to design a system strong enough to protect you from impulsive behavior.
The Psychology-First Framework for Making the “Perfect” Investment Decision
2. Define Your Decision Environment Before You Decide
Before looking at any price chart or asset:
Ask yourself three foundational questions (H3):
- What is my objective? (Growth, income, speculation, hedge?)
- What is my acceptable risk?
- What is my time horizon?
This clarity alone eliminates 70% of bad trades, because mistakes usually come from decisions made without a predefined context.
3. Build a Simple, Repeatable Checklist
A consistent checklist reduces emotional interference and improves accuracy.
Here’s a proven example:
Trading/Investment Decision Checklist (H3)
- Do I fully understand the asset or market?
- Is my entry based on analysis, not emotion?
- Where is my invalidation point (stop-loss or thesis-breaker)?
- Does the position size align with my risk tolerance?
- Is the timing appropriate, or am I reacting to noise?
The key is consistency — the perfect decision is rarely the one that feels exciting, but the one that follows your system.
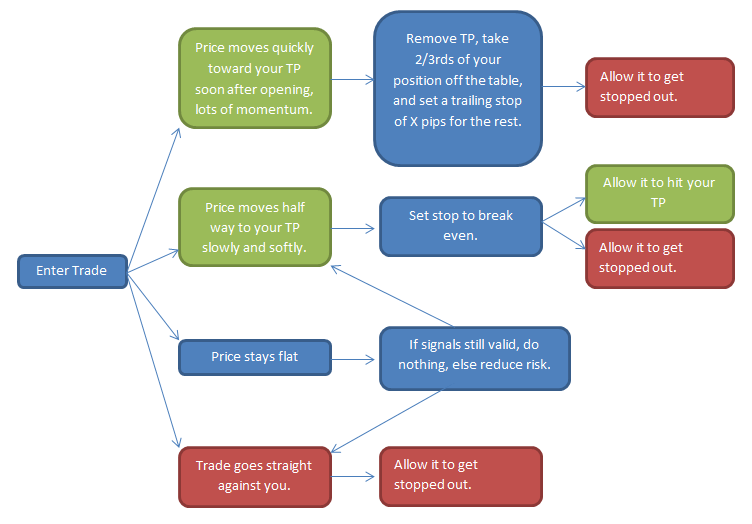
4. Use the 3A Method: Analyse, Anticipate, Act


Analyse
Examine fundamentals, technicals, sentiment, and macro context. Look for confluence, not perfection.
Anticipate
Define scenarios:
- What if price goes in my favor?
- What if it goes against me?
- What would a neutral or sideways environment look like?
This reduces panic during volatility because you’ve mentally pre-lived the possibilities.
Act
Execute with discipline. A good decision executed late becomes a bad one.
Use automation when possible: alerts, stop-loss, limit orders.
Read also: How Mindfulness Improves Your Investing Performance
5. Build Your Confidence Through Pre-Commitment
Investors who decide “in the moment” rely on emotion.
Investors who decide before the moment rely on strategy.
Use pre-commitment tools such as:
- Written trade plans
- Pre-market preparation
- Journaling entries and exits
- Defining the reason why this trade matters to you
Pre-commitment removes the ambiguity that typically causes hesitation.
6. The Perfect Decision Is Not the One That Wins — It’s the One That Follows Your Strategy
One of the biggest psychological errors is judging decisions only by outcomes.
A trade can be good and still lose money if conditions shift.
A trade can be bad and still win if luck intervenes.
Professional investors judge decisions based on process quality, because process is repeatable — luck is not.
Conclusion
Making the perfect investment or trade decision isn’t about predicting the market flawlessly. It’s about designing a rational, repeatable, and emotionally resilient process that protects you from impulsive choices and increases your consistency over time.
By understanding your emotional biases, clarifying your objectives, using a structured checklist, and applying the 3A Method, you transform uncertainty into confidence.
If you want to elevate your decision-making even further, start applying these steps to your next trade — and watch how your clarity improves.
Further Reading
- The Most Common Cognitive Biases That Destroy Investment Returns
- A Buffett-Style Behavioral Portfolio Framework (Step-by-Step)
- Financial Psychology: How Emotions and Cognitive Biases Shape Every Investment Decision
📖 Complete Guide: Psychology of Money & Financial Mindset: The Complete Guide

Written by
Monteiro
Investor · Behavioral Finance Writer · 20+ Years of Market Experience
life enthusiast, self-proclaimed scientist, philosopher, ...
📬 Enjoyed this article?
Follow along for new insights on behavioral finance, investor psychology, and long-term thinking.
3 thoughts on “Mastering Investment Decisions: A Psychological Approach”