
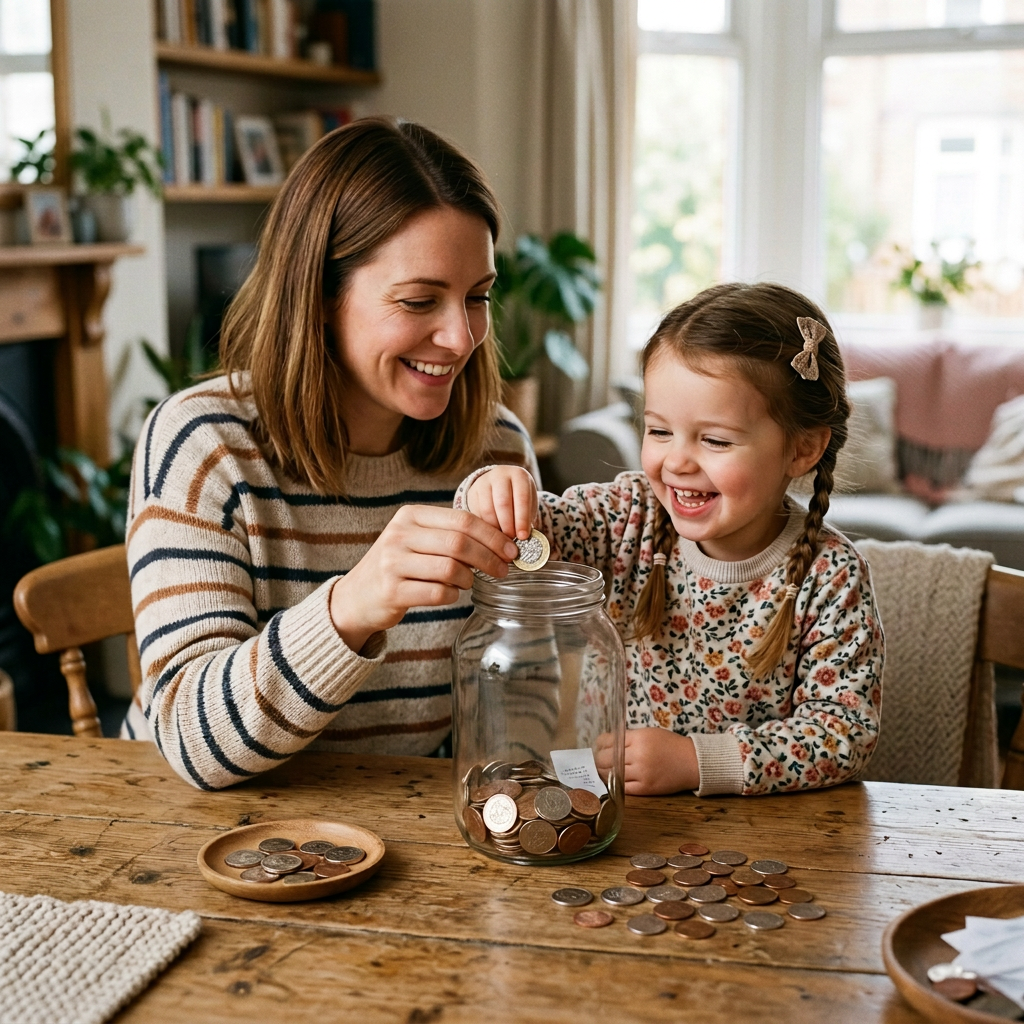
By age seven, children have developed the cognitive capacity to understand the core concepts of money — saving, spending, giving, earning. By adolescence, their money scripts — the unconscious beliefs about money that will drive their financial behavior for decades — are largely in place.
The window for financial education is not college or early adulthood. It’s childhood. And the most powerful financial education is not a formal curriculum. It’s the financial behavior children observe in the adults around them, translated through emotionally meaningful experiences.
What Children Actually Learn About Money
Children learn about money through three channels, in order of impact:
- Observation: What they see adults doing with money — how financial decisions are made, how financial stress is handled, what emotions accompany spending and saving
- Experience: Their own encounters with money — earning it, managing it, losing it, making decisions about it
- Instruction: What they’re explicitly told about money
Most financial education efforts focus almost entirely on the third channel — the least powerful of the three. Children whose parents talk about responsible saving while visibly panicking about bills, or preach frugality while spending impulsively, receive the first two channels loudly over the third.
📊 What Research Shows
Researchers at the University of Cambridge found that children’s core money habits are formed by age seven. A study tracking children from early childhood into adulthood found that the financial behaviors and attitudes observable at age seven were significantly predictive of financial behaviors at age 20 — including saving rates, impulse control around spending, and willingness to delay gratification for larger future rewards.
Age-Appropriate Financial Education
Ages 3-5: Naming and sorting
Children at this age can understand that coins and bills have different values, that things cost money, and that money comes from work. Simple games sorting coins, visiting the grocery store with an explicit conversation about prices, and having their own small piggy bank introduce the basic mechanics of money without overwhelming abstraction.
Ages 6-10: The three-jar system
One of the most evidence-backed early money education tools. Divide any money a child receives into three labeled jars: Spend, Save, Give. The ratios matter less than the habit of consciously allocating. This introduces delayed gratification (saving toward a goal), future-orientation, and generosity as embedded features of financial life — not afterthoughts.
Ages 10-14: Real responsibility
Children in this range benefit most from real financial responsibility — managing a clothing allowance, budgeting for a specific purchase, contributing to a family financial decision. The learning here is in experiencing consequences: spending the whole allowance on something impulsive and having nothing left for something they really wanted is more effective than any lecture about budgeting.
Ages 14-18: Investment basics and financial reality
Teenagers are ready to understand compound interest, basic investing concepts, credit mechanics, and — most importantly — the actual cost of their lifestyle. Showing a teenager the household budget, discussing the cost of their planned lifestyle, and introducing a small investing account (with real money, real decisions, and real consequences) provides financial education that no classroom can replicate.
🔑 Key Takeaway
The most important financial education you can give a child isn’t about money mechanics. It’s about their relationship to money — whether it feels scarce or abundant, frightening or manageable, a tool or a tyrant. That relationship is formed by watching you, not by lessons you teach them.
The Conversations That Matter Most
“We’re choosing not to buy that right now”
This framing — choice versus inability — subtly but powerfully shapes a child’s relationship to financial limits. “We can’t afford it” instills scarcity and powerlessness. “We’re choosing to save for our vacation instead” instills agency and prioritization.
Talking about mistakes
Parents who share their own financial mistakes — a poor investment, an impulsive purchase, a financial decision they’d make differently — give children two gifts: the normalization of financial imperfection, and a framework for learning from financial errors rather than being destroyed by shame about them.
The work-money connection
Children who understand that money comes from providing value — not just from employment, but from problem-solving, creating, and contributing — develop a fundamentally different relationship with earning than those who experience money as something that simply arrives (or doesn’t).
What Not to Do
- Using children as financial confidants for adult money stress (anxiety is contagious; protect children from financial worry that isn’t theirs to carry)
- Rewarding achievements with money rather than with recognition (this conflates self-worth with financial reward)
- Shielding children from all financial reality (they’ll encounter it eventually — better with guidance than without)
- Inconsistent rules (allowance as reward, then punishment, then forgotten) that teach that financial rules are arbitrary
📚 Recommended Reading
For practical, evidence-backed guidance on teaching children about money at every age, Make Your Kid a Money Genius (Even If You’re Not) by Beth Kobliner is the most accessible and research-grounded resource I’ve found — available in my Amazon reading list.
The Long Game
A child who learns to save toward a goal, give a portion of their money, understand trade-offs, and discuss money openly has a lifetime advantage over one who enters adulthood with money scripts formed entirely by observation of adult anxiety. The investment in your child’s financial intelligence is one of the highest-return investments available to any parent.
Continue the Money & Relationships Series: Financial Boundaries.

Written by
Monteiro
Investor · Behavioral Finance Writer · 20+ Years of Market Experience
life enthusiast, self-proclaimed scientist, philosopher, ...
📬 Enjoyed this article?
Follow along for new insights on behavioral finance, investor psychology, and long-term thinking.